Oʻahu’s flood maps changed on June 10, 2026. The updated Flood Insurance Rate Maps redrew flood risk along many streams across the island, and it’s the first major update to those maps in more than a decade. Some property owners now sit in a different flood zone than they did before.
If you already have an elevation certificate for your property, you might be asking a fair question. Does that certificate still tell you anything useful now that the map has changed? The short answer is that it often does, but not the way many people expect. A new map and an existing certificate are two different things, and knowing how they connect can save you time and confusion.
An Updated Map Does Not Automatically Update Your Elevation Certificate
A new flood map and an elevation certificate are not the same record. When FEMA updates a map, it changes how flood risk gets drawn across a whole area. The June 2026 update came out of years of stream studies, and it shifted the lines that mark flood zones on Oʻahu.
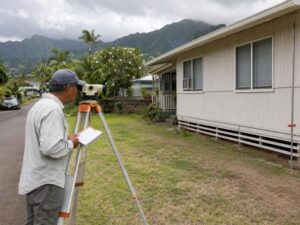
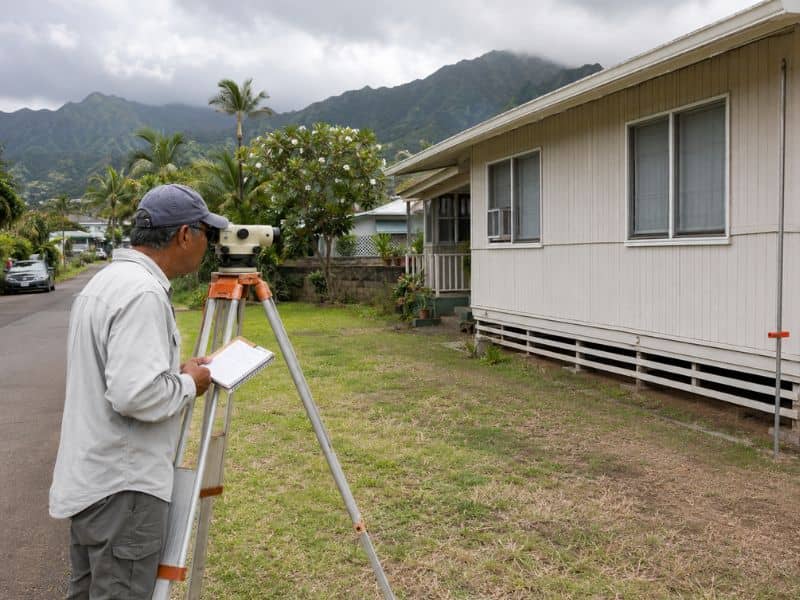
An elevation certificate works at a much smaller scale. It’s a FEMA form that a licensed surveyor, engineer or architect fills out for one specific building. It records real, measured elevations for that structure and the ground around it. Those numbers come from a field survey, not from a map.
So when the map changes, your certificate doesn’t change with it. The measured elevations on it stay the same. What can change is how those numbers get read against the new zone, and that’s a separate step.
What an Elevation Certificate Can Add to the New Map Picture
An elevation certificate adds something a flood map can’t show. The map tells you which zone a property sits in. The certificate tells you how high the building actually stands.
That measured height matters once the new zones are in place. A lender, an insurer or a City official may ask for the elevation of a structure compared with the flood level shown for its area. The certificate holds those exact figures for your property. Without it, all anyone has is the zone line on the map.
It helps to be clear about what a certificate does and doesn’t do. It records elevations. It does not, on its own, move your property into a different zone or set your insurance price. Rate decisions and zone questions involve other steps and other parties. The certificate gives them the property-specific numbers they need to work with.
When an Older Elevation Certificate Deserves a Closer Look
An older elevation certificate isn’t automatically out of date. Age alone doesn’t make it wrong. Still, a few situations make it worth checking whether the certificate you have fits the question in front of you.
Take a closer look when:
- You’ve made physical changes to the property, like new grading, fill or drainage work.
- Someone has altered the building or made major improvements to it.
- The June 2026 update placed your property in a new flood zone.
- A lender, insurer or City agency asks for current elevation information.
- The certificate you have doesn’t include the detail the current request calls for.
Whether an older certificate works comes down to how you plan to use it. One party may accept it as is. Another may want newer figures or added detail. The requirement sits with the person or agency asking, so it helps to know what they need before you decide the certificate is fine or falls short.
The Elevation Details That Matter After a Map Revision
When someone reviews an elevation certificate, they look at more than a single number. A certificate holds several elevations, and each one answers a different question.
A few details tend to get the most attention. First, the building and site elevations, which show how high the structure and the surrounding ground sit. Second, the datum, which is the starting point for every elevation on the form. If two certificates use different starting points, their numbers won’t line up, and that matters when you compare old and new records.
A reviewer also checks that the certificate actually belongs to your property and not a neighboring lot with a similar address. And they look at whether the figures still hold, or whether the site needs a fresh field check after grading or construction.
This is why one elevation number rarely tells the full story. A single figure can look fine on its own and still miss the context around it. The lowest floor, the ground next to the building and the reference point all work together, and a reviewer reads them as a set.
What Property Owners Should Do After the 2026 Map Update
If the map update has you wondering about your certificate, a simple order of steps keeps things clear.
Start by checking where your property falls on the current FEMA and City flood maps. The City encourages owners to review the updated maps now that they took effect on June 10, 2026. Once you know your current zone, find any elevation certificate or elevation records you already have on file.
Next, get clear on why the certificate matters right now. A home sale, a loan, an insurance question and a permit each call for different things. When you know the reason, ask that party directly. Your lender, insurer or the City can tell you whether the certificate you hold meets what they need today.
If it turns out you don’t have elevation figures for the property, or the ones you have need a fresh field check, that’s the point to bring in a licensed surveyor. A current certificate for the right property, tied to the right reference point, gives everyone accurate numbers to work from. That beats guessing from a map line alone.