Refinancing a resort is not the same process as buying one. But it can still bring a surveyor back to the property. Lenders funding a refinance often want their own picture of the land, the buildings, and anything built or changed since the last loan closed.
Why a Resort Refinance Can Bring the Survey Back Into the Deal
A purchase and a refinance are different events. In a purchase, the buyer and the buyer’s lender look at the property for the first time. In a refinance, the property already has an owner and a history. What changes is the lender.
A new lender did not fund the last loan and did not review the last survey. Its underwriting rules may call for a current ALTA/NSPS Land Title Survey before closing.
This is not an automatic step for every resort refinance. Some lenders accept an older survey, others want a new one. It depends on the loan amount, the lender’s internal policy, the title insurer’s position, and how much has changed on the property.
An older survey was accurate for the deal it was made for. It may not answer questions the new lender is asking now. The property might look the same from the outside, yet the survey this lender needs could still be a different document.
When an Older Resort Survey May No Longer Fit the Refinance
Having a survey on file does not mean that survey still works for a new loan. A survey is a record of the property at one point in time, and resorts change.
New buildings get added. Existing ones get expanded. Parking areas get reworked. Walkways, pools, and other site features get added or removed. Access points can shift. Any of these can matter to a lender that wants to know what it is financing today.
The right move is to compare the old survey to the property as it stands now. That is not something one party decides alone. The lender, title company, insurer, and surveyor all have a role in deciding whether the existing survey still works or a new one is needed.
There is no fixed rule stating that a survey expires after a set number of years. ALTA/NSPS standards do not set that kind of age limit. What matters is whether the survey still reflects the property and meets the requirements of this transaction.
Resort Changes That Can Make a Refinance Survey More Complicated
Resort properties tend to change more than a typical office building or retail site. That is part of what makes refinance surveys for resorts different from a routine update.
Things that can affect a refinance survey include:
- New or remodeled resort buildings
- Added structures or other site improvements
- Changes to parking layout or traffic flow
- Expanded pools, courts, or other recreational areas
- New walls, fences, or gates
- Changes that affect access routes or recorded interests
- Any improvement built after the last survey was completed
None of this means the property is a problem. It means the surveyor needs current field information to show what is actually there. A resort that looks the same on a site plan can still have real differences on the ground.
This applies to any resort, regardless of island or property type. New construction, added amenities, and site work all matter to a surveyor and a lender.
What to Give the Surveyor Before Ordering ALTA Surveys for a Resort
A refinance survey moves faster when the surveyor starts with the right records instead of chasing them down later. Before ordering the survey, gather:
- The current title commitment or other current title evidence
- The current legal description on record
- Recorded easements and any other recorded documents affecting the property
- The previous survey, if one exists
- A description of any major improvements made since that previous survey
- The lender’s written survey requirements
- Any Table A items the lender or title insurer wants included
The 2026 ALTA/NSPS Minimum Standard Detail Requirements for Land Title Surveys took effect February 23, 2026, replacing the 2021 standards. The survey request should name the current title evidence and other records needed, and state that a 2026 ALTA/NSPS survey is being requested along with the Table A items wanted.
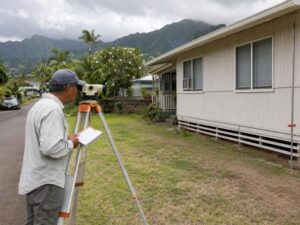
Land surveying is a licensed profession. The state tracks surveyor licenses through the Department of Commerce and Consumer Affairs, so a resort owner working on a refinance can confirm a surveyor’s license status there.
How to Keep the ALTA Survey From Becoming a Refinance Bottleneck
A survey does not have to slow down a refinance closing. A few habits help keep it on track.
Bring the survey question to the lender and title team early, not after the loan is already in underwriting. Get clear on what survey standard is being requested and which Table A items apply. Find out whether the existing survey can be used as is, updated, or needs to be replaced. Give the surveyor complete, current records rather than partial ones. Flag any construction or site changes before fieldwork begins, not after the surveyor is already on site.
Do not assume the survey from the original purchase will carry over. That assumption is one of the more common causes of last-minute delay in resort refinance closings.
Coordination between the owner, lender, title company, and surveyor keeps the schedule realistic. No single party controls how long a resort survey takes, since that depends on the size of the property and how much has changed.